Nike's market cap hit a peak of $280B in November 2021. It's now down to $57B (a $223B drop) and will be delisted from S&P 100.
Former Nike branding exec Massimo Giunco wrote a viral post in 2024 laying it all out. He blamed CEO John Donahoe (2020-2024) for going all in on direct-to-consumer (DTC)...with a cameo from McKinsey:
▫️ELIMINATE CATEGORIES: McKinsey advised Nike to get rid of categories (running, basketball, soccer) and re-classify everything into “Women”, “Men” and “Kids”.
The logic was that Nike was duplicating resources and a pivot to DTC would provide enough customer data to inform product decisions instead of relying on the category experts (eg. a basketball vet that spent 20+ years at Nike). A lot of these experts were fired and Nike lost their insights.
This was a clear L because Nike quietly brought back categories at end 2023.
▫️END WHOLESALE LEADERSHIP: Nike ended hundreds of relationships with wholesales partners and prioritized Nike's website over retail.
The change looked genius during COVID but as customers returned to brick ‘n mortar, Nike’s product were nowhere to be found. It had burnt bridges with partners, who were happy to give shelf space to upstarts (this wasn’t covered but I think On and Hoka took advantage of this for running)
There was also a lack of feedback from retailers, which led to inventory issues (the “data-driven” insights from online sales proved to not be a panacea).
▫️PRIORITIZE DIGITAL MARKETING: Nike changed its marketing budget to focus on driving users to Nike digital properties and membership platforms.
For decades, Nike spent 10% of sales on brand advertising to create an aspirational halo. The prioritization of programmatic ad spend meant Nike went from “create demand” (new customers) to “serve and retain demand” (re-targeting existing ones).
The result was a slowdown in sales.
“Because of that,” writes Massimo Giunco (who spent 21 years at the company), “Nike invested a material amount of dollars (billions) into something that was less effective but easier to be measured vs something that was more effective but less easy to be measured. In conclusion: an impressive waste of money.”
The quality of advertising was also...not great.
***
The focus on DTC is not surprising. Donahue was formerly CEO of B2B SAAS firm ServiceNow.
Nike’s DTC business peaked at 44% of sales in 2024 (vs. under 30% before the strategy change).
The digital focus seems to have commoditized the product, impacted Nike’s brand perception and created an opening for competitors.
***
Original post: https://www.linkedin.com/pulse/nike-epic-saga-value-destruction-massimo-giunco-llplf/
Nike's disastrous pivot to direct-to-consumer sales has culminated in a humiliating exit from the S&P 100.
China still refines 90%+ of the world’s rare earths.Tesla just built a production EV motor that uses none of them.
The Cybercab drive unit contains zero neodymium, praseodymium, dysprosium, or terbium. Elon Musk says it still matches full vehicle range. He called that “extremely hard to achieve.”
The 163 kW unit is 18% smaller, 25% lighter, and designed for fully automated, sub-10-second assembly.
Most EV motors still depend on Chinese-processed magnets that can account for 25–35% of motor material cost. This one doesn’t.
The Austin fleet is small, and Tesla’s other cars still use rare-earth motors. Wind, robots, and defense still need those magnets.
But the monopoly is no longer a technical requirement. A high-efficiency traction motor can now be built without going through China’s refining system.That is the part that matters.
Tesla's engineering breakthrough on the Cybercab severs a critical supply chain vulnerability tied to Chinese rare earth monopolies.
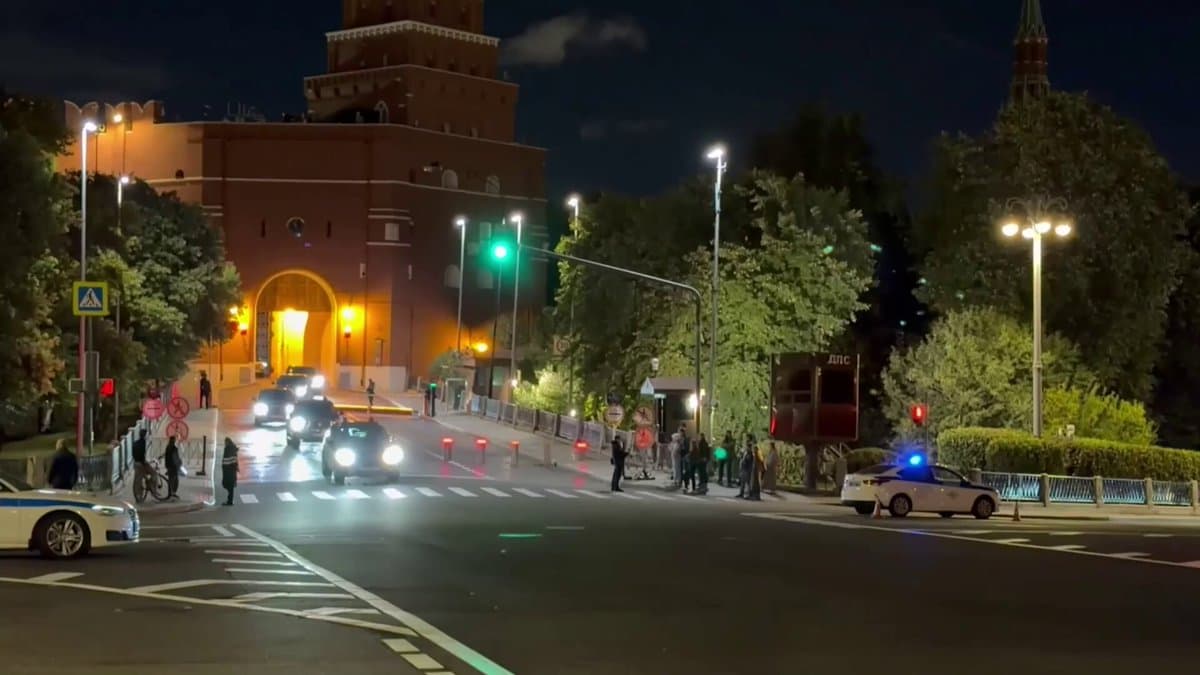
🇷🇺🇺🇸 Witkoff and Kushner have left the Kremlin after roughly 3.5 hours with Putin.
No statements. No readout.
Now they’re heading to Kyiv to meet Ukrainian officials.
Whatever was said in that room is traveling with them.
Source: @TabzLIVE on TG / Writer: Oliver
Back-channel diplomacy between the incoming Trump administration and Moscow is accelerating as key envoys shuttle directly to Kyiv.
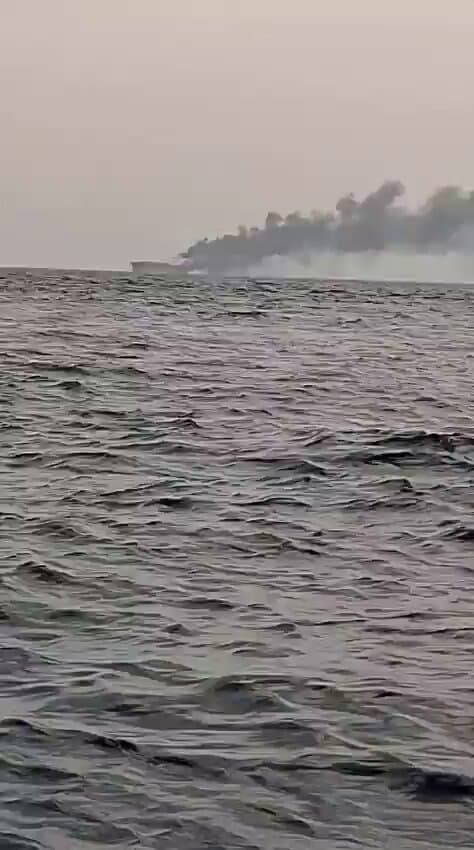
IRIB claims Iran targeted three vessels in the Strait of Hormuz and three American ships. Tehran says the strike is retaliation for U.S. attacks on three Iranian tankers.
A rapid escalation in the Strait of Hormuz threatens global energy markets as Tehran directly engages American naval assets.
"We have to accept the possibility that all mathematics could fall to AI within some months, however unsettling that might seem."
The part of mathematics that is like playing Chess or Go, coming up with ever cleverer moves, will be conquered by AI. That is now evident.
The part of mathematics that is like inventing an entire new game like Chess _that humans would consider interesting_ is much harder but then humans do that very very rarely too. The "humans would consider interesting" could be considered a fundamental limit of AI or merely a face-saving formula to protect human ego but humans set the rules (for now!).
Where does programming fit here? It increasingly seems to me that a very large fraction of software code could be produced competently and _correctly_ by AI. The "correctly" part is being addressed with proof systems like Lean that are applied to mathematical theorem proving today but soon will be applied to verify the software code produced by AI.
The point is not that "AI will do it all". There will be humans involved in the process. The key question is "how many humans are needed" and the answer right now is sobering and unsettling.
All of us in software need to figure out how to stay relevant. Let me get back to work. Please wish us luck 🙏
The rapid advancement of reasoning models is forcing tech leaders to confront the imminent automation of high-level mathematics.
People who think Office, Teams, or Outlook coming to Linux as native apps are stuck in a pre-@satyanadella idea of Microsoft. This was the memo 10 years ago!! https://www.microsoft.com/en-us/windows-server/blog/2015/05/06/microsoft-loves-linux/
Microsoft bringing its core productivity suite natively to Linux completes a decade-long cultural pivot initiated by Satya Nadella.
Claude Fable 5.1 (Max) by @AnthropicAI has landed in the Agent Arena at #1 with +15.8% net improvement across 6.7k+ real-world agentic sessions! It also redraws the price-performance frontier: #1 on the leaderboard at a median cost of $4.14/task.
By signal, Claude Fable 5.1 sees a massive lead in implicit user sentiment with an astonishing (+42.5%) in Praise vs. Complaint. Users are praising it around 2x more often than the next top model. It also sees strong explicit feedback via Confirmed Success (+22.4%), and solid Bash Recovery (+13.1%), with no Tool Hallucinations. More detail on its performance by signal below.
Claude Fable 5.1 (Max) out ranks all past Claude variants and the rest of the pack by a healthy lead.
In Agent Arena, we measure models on millions of long-horizon agentic tasks from a global community of users. Models can access web search, filesystem, and terminal tools to complete complex workflows. The leaderboard measures model performance on outcomes relative to the average model using a causal tracing methodology.
Stay tuned as traces continue to come in for the latest GPT-6 Astra to see how it compares. Use Agent Mode to contribute to the real-world rankings.
Congrats again to @AnthropicAI for this release.
Anthropic's newest model is dominating agentic benchmarks while drastically undercutting competitors on price.
Timepass talk on Sunday
1. Supriya Lifescience
FY27 is projected to be a transformative growth year, with management maintaining firm guidance to reach the ₹1,000 crore revenue milestone while targeting normalized EBITDA margins of 33% to 35%.
Despite initial Q1 FY27 disruptions caused by transient headwinds like water scarcity at Lote and solar policy changes, performance is expected to recover non-linearly. Growth will be heavily back-ended in H2 FY27 as production normalizes, inventory liquidates, and deferred Q1 sales of ₹35 crore are recovered without major operational downtime from annual maintenance.
Management also clarified that that the customs issue was limited strictly to this specific shipment, does not impact other exports or product licenses, and will have no material impact on operations or financial guidance. The company has already received a fresh CBN export permit to regularize the consignment.
The primary revenue drivers for the year center around new product commercialization and expanding therapeutic focus areas.
Key catalysts include the scale-up of two recently launched liquid anesthetic inhalation products, upcoming pipeline launches in the ADHD segment, and the H2 FY27 launch of contrast media products (iohexol). These additions build upon healthy momentum across core product portfolios, such as cardiovascular advanced intermediates and established lines in anesthetics, anti-anxiety, vitamins, and anti-diabetics. Furthermore, a strong export footprint, which accounts for 81% of revenue, along with deep backward integration (72% fully integrated) provides significant structural support to protect profit margins.
Longer-term infrastructure and regulatory milestones scheduled throughout FY27 will further bolster execution and open new market corridors.
The newly operational Ambernath facility is advancing its CMO/CDMO vertical for finished formulations (tablets, injectables) following scheduled regulated market audits, such as the EU audit in late November 2026.
Simultaneously, initial phase construction is underway at the Patalganga (Isambe) facility, backed by a ₹200 crore Phase-1 CapEx allocation for new API and intermediate blocks, to expand long-term production capacity. Coupled with upcoming CEP approvals for European markets and ongoing SAP digital integration, these developments establish a robust structural foundation for sustainable growth through FY27 and beyond.
The company also indicated that it has made good progress on a large anesthetic CDMO contract and is now very close to signing a term sheet. If timelines hold, it expects to make a positive announcement in the next quarter.
2. MRI, Gadolinium and Manganese
Approximately one-third of all MRI scans worldwide (~65 million procedures annually) require a contrast agent to clearly visualize tumors, lesions, vascular abnormalities, or tissue damage.
Gadolinium-Based Contrast Agents (GBCAs) like gadobutrol are the most commonly used.
However, GBCAs carry couple of disadvantages
i). Because gadolinium is a non-essential heavy metal, small traces can remain deposited in human bones, brain tissue, and skin, posing potential risks for pediatric patients or individuals requiring frequent follow-up scans.
ii). As a rare-earth element, gadolinium's global supply chain is heavily concentrated in China, leaving healthcare systems around the world vulnerable to geopolitical trade disruptions and supply shortages for critical diagnostic imaging.
The Alternative: GE HealthCare’s novel investigational agent, mangaciclanol, replaces traditional gadolinium with manganese, a naturally occurring, body-regulated mineral, and has earned FDA Fast Track designation as it advances through Phase 2/3 LUMINA clinical trials to offer a safer, environmentally friendly, and supply-resilient alternative for contrast-enhanced MRI scans in both adult and pediatric patients.
Because manganese is an essential nutrient already metabolized by the body, macrocyclic manganese agents offer a significantly safer profile.
If this approval is thru, it would be good for all patients needing to go thru MRI scans!
Of course, this could be 2-3 years away!
3. The $55 Trillion Nuclear Supercycle
Jefferies initiated coverage on the global nuclear sector, framing it as entering its strongest growth cycle in four decades. Citing compounding power demand from hyperscale data centers, physical AI, and widespread electrification, the brokerage estimates roughly $55 trillion in global nuclear-related capex through 2100, including $9 trillion by 2050 to replace aging global reactor fleets. Recognizing structural supply deficits in primary fuel, Jefferies raised its long-term uranium price outlook and issued Buy ratings on key global miners, developers, and specialized component makers like Cameco, NexGen Energy, and BWX Technologies.
This massive structural capex creates high-margin second-order opportunities for manufacturing, engineering, and infrastructure suppliers. Nuclear plant construction relies heavily on precision-engineered components, specialized metallurgy, and high-pressure flow control systems that must meet stringent nuclear regulatory standards. Companies in adjacent sectors, such as high-grade alloy forging, specialized pipe spooling, custom mechanical sealing, and high-voltage grid transmission, stand to gain pricing power and margin expansion as localized supply chains scale up to build both traditional Pressurised Heavy Water Reactors (PHWRs) and next-generation Small Modular Reactors (SMRs).
Of course, India itself has articulated an ambition of ~100 GW nuclear capacity by 2047 (from ~8 GW currently), implying a significant scale-up over the next two decades.
In India, several companies are prime candidates to capture these indirect equipment and infrastructure tailwinds if and when the supply chain expands to India.
It’s quite evident that Larsen & Toubro and Bharat Heavy Electricals Limited lead the pack. In particular, the scale and contribution of L&T is truly impressive.
Walchandnagar Industries: Appears to be a relatively pure-play on the nuclear segment. However, the lack of concalls and regular investor communication makes it difficult to assess the company’s direction and execution.
Kilburn Engineering: Around 1/4th of its order book is from the nuclear power segment. It supplies pump room coolers, vault coolers and heavy-water vapour recovery systems.
MTAR Technologies: A specialized player supplying components for fuel transfer systems.
KSB Pumps: Another specialized supplier, particularly in coolant pumps. Earlier this year, it also received an export order from Europe.
Unimech Aerospace: Has an interesting nuclear order book and is qualified across 10 different subsystems, which could provide multiple avenues for growth.
Again, nuclear is a long-gestation theme, and the actual earnings curve can differ significantly from one player to another.
The opportunity may be large, but the timing of revenue, order conversion and earnings will not be uniform across companies.
4. Thermax
Thermax faced a challenging Q1 FY27 primarily due to a severe financial hit in its Industrial Infra segment, where a cost-to-completion revision on a legacy, loss-making government EPC project resulted in an unexpected hit of ₹91 crore. This was triggered by late structural design changes mandated by an external engineering partner.
Operational execution was further hindered by shipping delays of finished goods inventory worth approximately ₹300 crore, largely caused by high freight rates and Middle East logistics disruptions, which postponed revenue recognition. Profitability was additionally compressed by an ₹18 crore rise in raw material commodity costs (mainly steel), alongside a ₹20 crore loss in First Energy Private Limited (FEPL) due to bureaucratic approval delays on completed Tamil Nadu projects and high manpower carrying costs.
Outlook for the Rest of FY27
Despite the weak start, management remains bullish on the rest of FY27, citing a strong and high-quality order backlog that will drive robust revenue and margin conversion in Q2, Q3, and Q4. Revenue execution is expected to ramp up significantly, with the company aiming to achieve quarterly revenues exceeding ₹3,000 crore for two to three of the remaining quarters.
Furthermore, profitability is projected to recover sharply as high-margin international export orders (such as U.S. data center equipment shipments) get recognized, commodity price pressures flush out of Industrial Products, and legacy government/FGD project exposures systematically wrap up to near-zero by the end of the fiscal year.
On August 6, 2026, the Union Cabinet approved GOBARdhan (National Circular Bioenergy Scheme) with a total outlay of ₹23,731 crore ($2.5 billion).
The policy, effective September 1, 2026 through FY2035–36, offers several incentives, including a significant increase in the procurement price to ₹2,110/MMBTU, up from ₹1,478/MMBTU. This should now open up good pipeline for Thermax.
Future Growth Drivers
Thermax’s multi-year growth trajectory is anchored across several key segments:
Data Center Infrastructure & Export Expansion: The company is expanding high-margin cooling solutions (absorption chillers and hybrid CLCTs) and specialized boiler pressure parts for power projects serving U.S. and Indian data centers.
Thermal Power & TBWES Capacity: Surging national and global demand for thermal, captive power, and subcritical/supercritical boiler capacity is driving a substantial pipeline, prompting Thermax to expand internal manufacturing and ecosystem capacity.
Clean Energy & Green Solutions: Thermax is positioned to capture policy-driven growth in Bio-CNG (via expected central pricing and mandate revisions), Green Methanol (underway with its showcase Kandla Port project), and Green Hydrogen/SOEC demo technology through its partnership with HydrogenPro.
Industrial Products & Green Upgrades: Core double-digit growth is sustained through industrial sustainability requirements, particularly Zero Liquid Discharge (ZLD) water plants, industrial air pollution control retrofits, and high-margin utility offerings via Thermax Onsite Energy Solutions Limited (TOESL).
5. Avalon Technologies
Avalon Technologies announced a joint venture (JV) with Germany-based Zollner Elektronik AG, one of Europe’s largest Electronics Manufacturing Services (EMS) players.
The entity will be incorporated as Zollner Avalon Private Limited and will serve as an India-based manufacturing platform for high-complexity electronics.
Core Structure & Equity Mechanics
Initial Ownership Split: Zollner will hold 51% and Avalon will hold 49%.
Call Option for Majority Stake: Avalon retains a call option to acquire an additional 2% stake (taking its shareholding to 51%) after the 3rd anniversary of commercial production commencing at the plant, contingent on agreed valuation parameters.
Although Avalon is a 49% minority shareholder, meaning the JV's top-line revenue and EBITDA won't directly consolidate into Avalon’s primary P&L lines, its 49% share of net profits will directly boost PAT via equity accounting.
Beyond its 49% equity share, Avalon will act as a direct component supplier to the JV, supplying cable wiring & harnesses, magnetics, plastics, sheet metal, and precision machining. This creates a dual revenue stream (equity share + component vendor supply).
Zollner brings six decades of German engineering practices, specifically in high-density, complex Surface Mount Technology (SMT) and multi-layered Printed Circuit Board Assembly (PCBA) processes.
Likewise, Zollner operates extensively in lifecycle management, advanced automated optical/X-ray inspection systems, and high-reliability functional testing suited for mission-critical applications.
Operating alongside a Top-10 global EMS player transfers operational "know-how", including German manufacturing quality control, traceability protocols, and supply chain standardization, directly into the JV's Indian operations.
Expansion into Strict Industry Verticals
Healthcare & Life Sciences: Medical-grade electronics require specialized manufacturing standards (such as ISO 13485 certifications) and zero-defect quality systems that Zollner operates globally.
Rail & Transport Infrastructure: High-reliability mechatronic assemblies that can withstand extreme vibration and temperature ranges.
Test & Measurement: Ultra-high precision, low-noise electronic boards.
Net-net, this could turn out to be a good JV!
That's all for this edition. Have a great Sunday!
Disclaimer: None or buy or sell recommendations. This publicly available information is shared for learning and education purposes.
Investors are closely watching Supriya Lifescience as it attempts to rebound from operational hiccups and hit ambitious revenue targets.
Nike's market cap hit a peak of $280B in November 2021. It's now down to $57B (a $223B drop) and will be delisted from S&P 100.
Former Nike branding exec Massimo Giunco wrote a viral post in 2024 laying it all out. He blamed CEO John Donahoe (2020-2024) for going all in on direct-to-consumer (DTC)...with a cameo from McKinsey:
▫️ELIMINATE CATEGORIES: McKinsey advised Nike to get rid of categories (running, basketball, soccer) and re-classify everything into “Women”, “Men” and “Kids”.
The logic was that Nike was duplicating resources and a pivot to DTC would provide enough customer data to inform product decisions instead of relying on the category experts (eg. a basketball vet that spent 20+ years at Nike). A lot of these experts were fired and Nike lost their insights.
This was a clear L because Nike quietly brought back categories at end 2023.
▫️END WHOLESALE LEADERSHIP: Nike ended hundreds of relationships with wholesales partners and prioritized Nike's website over retail.
The change looked genius during COVID but as customers returned to brick ‘n mortar, Nike’s product were nowhere to be found. It had burnt bridges with partners, who were happy to give shelf space to upstarts (this wasn’t covered but I think On and Hoka took advantage of this for running)
There was also a lack of feedback from retailers, which led to inventory issues (the “data-driven” insights from online sales proved to not be a panacea).
▫️PRIORITIZE DIGITAL MARKETING: Nike changed its marketing budget to focus on driving users to Nike digital properties and membership platforms.
For decades, Nike spent 10% of sales on brand advertising to create an aspirational halo. The prioritization of programmatic ad spend meant Nike went from “create demand” (new customers) to “serve and retain demand” (re-targeting existing ones).
The result was a slowdown in sales.
“Because of that,” writes Massimo Giunco (who spent 21 years at the company), “Nike invested a material amount of dollars (billions) into something that was less effective but easier to be measured vs something that was more effective but less easy to be measured. In conclusion: an impressive waste of money.”
The quality of advertising was also...not great.
***
The focus on DTC is not surprising. Donahue was formerly CEO of B2B SAAS firm ServiceNow.
Nike’s DTC business peaked at 44% of sales in 2024 (vs. under 30% before the strategy change).
The digital focus seems to have commoditized the product, impacted Nike’s brand perception and created an opening for competitors.
***
Original post: https://www.linkedin.com/pulse/nike-epic-saga-value-destruction-massimo-giunco-llplf/
Nike's disastrous pivot to direct-to-consumer sales has culminated in a humiliating exit from the S&P 100.
🇷🇺🇺🇸 Witkoff and Kushner have left the Kremlin after roughly 3.5 hours with Putin.
No statements. No readout.
Now they’re heading to Kyiv to meet Ukrainian officials.
Whatever was said in that room is traveling with them.
Source: @TabzLIVE on TG / Writer: Oliver
Back-channel diplomacy between the incoming Trump administration and Moscow is accelerating as key envoys shuttle directly to Kyiv.
"We have to accept the possibility that all mathematics could fall to AI within some months, however unsettling that might seem."
The part of mathematics that is like playing Chess or Go, coming up with ever cleverer moves, will be conquered by AI. That is now evident.
The part of mathematics that is like inventing an entire new game like Chess _that humans would consider interesting_ is much harder but then humans do that very very rarely too. The "humans would consider interesting" could be considered a fundamental limit of AI or merely a face-saving formula to protect human ego but humans set the rules (for now!).
Where does programming fit here? It increasingly seems to me that a very large fraction of software code could be produced competently and _correctly_ by AI. The "correctly" part is being addressed with proof systems like Lean that are applied to mathematical theorem proving today but soon will be applied to verify the software code produced by AI.
The point is not that "AI will do it all". There will be humans involved in the process. The key question is "how many humans are needed" and the answer right now is sobering and unsettling.
All of us in software need to figure out how to stay relevant. Let me get back to work. Please wish us luck 🙏
The rapid advancement of reasoning models is forcing tech leaders to confront the imminent automation of high-level mathematics.
Claude Fable 5.1 (Max) by @AnthropicAI has landed in the Agent Arena at #1 with +15.8% net improvement across 6.7k+ real-world agentic sessions! It also redraws the price-performance frontier: #1 on the leaderboard at a median cost of $4.14/task.
By signal, Claude Fable 5.1 sees a massive lead in implicit user sentiment with an astonishing (+42.5%) in Praise vs. Complaint. Users are praising it around 2x more often than the next top model. It also sees strong explicit feedback via Confirmed Success (+22.4%), and solid Bash Recovery (+13.1%), with no Tool Hallucinations. More detail on its performance by signal below.
Claude Fable 5.1 (Max) out ranks all past Claude variants and the rest of the pack by a healthy lead.
In Agent Arena, we measure models on millions of long-horizon agentic tasks from a global community of users. Models can access web search, filesystem, and terminal tools to complete complex workflows. The leaderboard measures model performance on outcomes relative to the average model using a causal tracing methodology.
Stay tuned as traces continue to come in for the latest GPT-6 Astra to see how it compares. Use Agent Mode to contribute to the real-world rankings.
Congrats again to @AnthropicAI for this release.
Anthropic's newest model is dominating agentic benchmarks while drastically undercutting competitors on price.
China still refines 90%+ of the world’s rare earths.Tesla just built a production EV motor that uses none of them.
The Cybercab drive unit contains zero neodymium, praseodymium, dysprosium, or terbium. Elon Musk says it still matches full vehicle range. He called that “extremely hard to achieve.”
The 163 kW unit is 18% smaller, 25% lighter, and designed for fully automated, sub-10-second assembly.
Most EV motors still depend on Chinese-processed magnets that can account for 25–35% of motor material cost. This one doesn’t.
The Austin fleet is small, and Tesla’s other cars still use rare-earth motors. Wind, robots, and defense still need those magnets.
But the monopoly is no longer a technical requirement. A high-efficiency traction motor can now be built without going through China’s refining system.That is the part that matters.
Tesla's engineering breakthrough on the Cybercab severs a critical supply chain vulnerability tied to Chinese rare earth monopolies.
IRIB claims Iran targeted three vessels in the Strait of Hormuz and three American ships. Tehran says the strike is retaliation for U.S. attacks on three Iranian tankers.
A rapid escalation in the Strait of Hormuz threatens global energy markets as Tehran directly engages American naval assets.
People who think Office, Teams, or Outlook coming to Linux as native apps are stuck in a pre-@satyanadella idea of Microsoft. This was the memo 10 years ago!! https://www.microsoft.com/en-us/windows-server/blog/2015/05/06/microsoft-loves-linux/
Microsoft bringing its core productivity suite natively to Linux completes a decade-long cultural pivot initiated by Satya Nadella.
Timepass talk on Sunday
1. Supriya Lifescience
FY27 is projected to be a transformative growth year, with management maintaining firm guidance to reach the ₹1,000 crore revenue milestone while targeting normalized EBITDA margins of 33% to 35%.
Despite initial Q1 FY27 disruptions caused by transient headwinds like water scarcity at Lote and solar policy changes, performance is expected to recover non-linearly. Growth will be heavily back-ended in H2 FY27 as production normalizes, inventory liquidates, and deferred Q1 sales of ₹35 crore are recovered without major operational downtime from annual maintenance.
Management also clarified that that the customs issue was limited strictly to this specific shipment, does not impact other exports or product licenses, and will have no material impact on operations or financial guidance. The company has already received a fresh CBN export permit to regularize the consignment.
The primary revenue drivers for the year center around new product commercialization and expanding therapeutic focus areas.
Key catalysts include the scale-up of two recently launched liquid anesthetic inhalation products, upcoming pipeline launches in the ADHD segment, and the H2 FY27 launch of contrast media products (iohexol). These additions build upon healthy momentum across core product portfolios, such as cardiovascular advanced intermediates and established lines in anesthetics, anti-anxiety, vitamins, and anti-diabetics. Furthermore, a strong export footprint, which accounts for 81% of revenue, along with deep backward integration (72% fully integrated) provides significant structural support to protect profit margins.
Longer-term infrastructure and regulatory milestones scheduled throughout FY27 will further bolster execution and open new market corridors.
The newly operational Ambernath facility is advancing its CMO/CDMO vertical for finished formulations (tablets, injectables) following scheduled regulated market audits, such as the EU audit in late November 2026.
Simultaneously, initial phase construction is underway at the Patalganga (Isambe) facility, backed by a ₹200 crore Phase-1 CapEx allocation for new API and intermediate blocks, to expand long-term production capacity. Coupled with upcoming CEP approvals for European markets and ongoing SAP digital integration, these developments establish a robust structural foundation for sustainable growth through FY27 and beyond.
The company also indicated that it has made good progress on a large anesthetic CDMO contract and is now very close to signing a term sheet. If timelines hold, it expects to make a positive announcement in the next quarter.
2. MRI, Gadolinium and Manganese
Approximately one-third of all MRI scans worldwide (~65 million procedures annually) require a contrast agent to clearly visualize tumors, lesions, vascular abnormalities, or tissue damage.
Gadolinium-Based Contrast Agents (GBCAs) like gadobutrol are the most commonly used.
However, GBCAs carry couple of disadvantages
i). Because gadolinium is a non-essential heavy metal, small traces can remain deposited in human bones, brain tissue, and skin, posing potential risks for pediatric patients or individuals requiring frequent follow-up scans.
ii). As a rare-earth element, gadolinium's global supply chain is heavily concentrated in China, leaving healthcare systems around the world vulnerable to geopolitical trade disruptions and supply shortages for critical diagnostic imaging.
The Alternative: GE HealthCare’s novel investigational agent, mangaciclanol, replaces traditional gadolinium with manganese, a naturally occurring, body-regulated mineral, and has earned FDA Fast Track designation as it advances through Phase 2/3 LUMINA clinical trials to offer a safer, environmentally friendly, and supply-resilient alternative for contrast-enhanced MRI scans in both adult and pediatric patients.
Because manganese is an essential nutrient already metabolized by the body, macrocyclic manganese agents offer a significantly safer profile.
If this approval is thru, it would be good for all patients needing to go thru MRI scans!
Of course, this could be 2-3 years away!
3. The $55 Trillion Nuclear Supercycle
Jefferies initiated coverage on the global nuclear sector, framing it as entering its strongest growth cycle in four decades. Citing compounding power demand from hyperscale data centers, physical AI, and widespread electrification, the brokerage estimates roughly $55 trillion in global nuclear-related capex through 2100, including $9 trillion by 2050 to replace aging global reactor fleets. Recognizing structural supply deficits in primary fuel, Jefferies raised its long-term uranium price outlook and issued Buy ratings on key global miners, developers, and specialized component makers like Cameco, NexGen Energy, and BWX Technologies.
This massive structural capex creates high-margin second-order opportunities for manufacturing, engineering, and infrastructure suppliers. Nuclear plant construction relies heavily on precision-engineered components, specialized metallurgy, and high-pressure flow control systems that must meet stringent nuclear regulatory standards. Companies in adjacent sectors, such as high-grade alloy forging, specialized pipe spooling, custom mechanical sealing, and high-voltage grid transmission, stand to gain pricing power and margin expansion as localized supply chains scale up to build both traditional Pressurised Heavy Water Reactors (PHWRs) and next-generation Small Modular Reactors (SMRs).
Of course, India itself has articulated an ambition of ~100 GW nuclear capacity by 2047 (from ~8 GW currently), implying a significant scale-up over the next two decades.
In India, several companies are prime candidates to capture these indirect equipment and infrastructure tailwinds if and when the supply chain expands to India.
It’s quite evident that Larsen & Toubro and Bharat Heavy Electricals Limited lead the pack. In particular, the scale and contribution of L&T is truly impressive.
Walchandnagar Industries: Appears to be a relatively pure-play on the nuclear segment. However, the lack of concalls and regular investor communication makes it difficult to assess the company’s direction and execution.
Kilburn Engineering: Around 1/4th of its order book is from the nuclear power segment. It supplies pump room coolers, vault coolers and heavy-water vapour recovery systems.
MTAR Technologies: A specialized player supplying components for fuel transfer systems.
KSB Pumps: Another specialized supplier, particularly in coolant pumps. Earlier this year, it also received an export order from Europe.
Unimech Aerospace: Has an interesting nuclear order book and is qualified across 10 different subsystems, which could provide multiple avenues for growth.
Again, nuclear is a long-gestation theme, and the actual earnings curve can differ significantly from one player to another.
The opportunity may be large, but the timing of revenue, order conversion and earnings will not be uniform across companies.
4. Thermax
Thermax faced a challenging Q1 FY27 primarily due to a severe financial hit in its Industrial Infra segment, where a cost-to-completion revision on a legacy, loss-making government EPC project resulted in an unexpected hit of ₹91 crore. This was triggered by late structural design changes mandated by an external engineering partner.
Operational execution was further hindered by shipping delays of finished goods inventory worth approximately ₹300 crore, largely caused by high freight rates and Middle East logistics disruptions, which postponed revenue recognition. Profitability was additionally compressed by an ₹18 crore rise in raw material commodity costs (mainly steel), alongside a ₹20 crore loss in First Energy Private Limited (FEPL) due to bureaucratic approval delays on completed Tamil Nadu projects and high manpower carrying costs.
Outlook for the Rest of FY27
Despite the weak start, management remains bullish on the rest of FY27, citing a strong and high-quality order backlog that will drive robust revenue and margin conversion in Q2, Q3, and Q4. Revenue execution is expected to ramp up significantly, with the company aiming to achieve quarterly revenues exceeding ₹3,000 crore for two to three of the remaining quarters.
Furthermore, profitability is projected to recover sharply as high-margin international export orders (such as U.S. data center equipment shipments) get recognized, commodity price pressures flush out of Industrial Products, and legacy government/FGD project exposures systematically wrap up to near-zero by the end of the fiscal year.
On August 6, 2026, the Union Cabinet approved GOBARdhan (National Circular Bioenergy Scheme) with a total outlay of ₹23,731 crore ($2.5 billion).
The policy, effective September 1, 2026 through FY2035–36, offers several incentives, including a significant increase in the procurement price to ₹2,110/MMBTU, up from ₹1,478/MMBTU. This should now open up good pipeline for Thermax.
Future Growth Drivers
Thermax’s multi-year growth trajectory is anchored across several key segments:
Data Center Infrastructure & Export Expansion: The company is expanding high-margin cooling solutions (absorption chillers and hybrid CLCTs) and specialized boiler pressure parts for power projects serving U.S. and Indian data centers.
Thermal Power & TBWES Capacity: Surging national and global demand for thermal, captive power, and subcritical/supercritical boiler capacity is driving a substantial pipeline, prompting Thermax to expand internal manufacturing and ecosystem capacity.
Clean Energy & Green Solutions: Thermax is positioned to capture policy-driven growth in Bio-CNG (via expected central pricing and mandate revisions), Green Methanol (underway with its showcase Kandla Port project), and Green Hydrogen/SOEC demo technology through its partnership with HydrogenPro.
Industrial Products & Green Upgrades: Core double-digit growth is sustained through industrial sustainability requirements, particularly Zero Liquid Discharge (ZLD) water plants, industrial air pollution control retrofits, and high-margin utility offerings via Thermax Onsite Energy Solutions Limited (TOESL).
5. Avalon Technologies
Avalon Technologies announced a joint venture (JV) with Germany-based Zollner Elektronik AG, one of Europe’s largest Electronics Manufacturing Services (EMS) players.
The entity will be incorporated as Zollner Avalon Private Limited and will serve as an India-based manufacturing platform for high-complexity electronics.
Core Structure & Equity Mechanics
Initial Ownership Split: Zollner will hold 51% and Avalon will hold 49%.
Call Option for Majority Stake: Avalon retains a call option to acquire an additional 2% stake (taking its shareholding to 51%) after the 3rd anniversary of commercial production commencing at the plant, contingent on agreed valuation parameters.
Although Avalon is a 49% minority shareholder, meaning the JV's top-line revenue and EBITDA won't directly consolidate into Avalon’s primary P&L lines, its 49% share of net profits will directly boost PAT via equity accounting.
Beyond its 49% equity share, Avalon will act as a direct component supplier to the JV, supplying cable wiring & harnesses, magnetics, plastics, sheet metal, and precision machining. This creates a dual revenue stream (equity share + component vendor supply).
Zollner brings six decades of German engineering practices, specifically in high-density, complex Surface Mount Technology (SMT) and multi-layered Printed Circuit Board Assembly (PCBA) processes.
Likewise, Zollner operates extensively in lifecycle management, advanced automated optical/X-ray inspection systems, and high-reliability functional testing suited for mission-critical applications.
Operating alongside a Top-10 global EMS player transfers operational "know-how", including German manufacturing quality control, traceability protocols, and supply chain standardization, directly into the JV's Indian operations.
Expansion into Strict Industry Verticals
Healthcare & Life Sciences: Medical-grade electronics require specialized manufacturing standards (such as ISO 13485 certifications) and zero-defect quality systems that Zollner operates globally.
Rail & Transport Infrastructure: High-reliability mechatronic assemblies that can withstand extreme vibration and temperature ranges.
Test & Measurement: Ultra-high precision, low-noise electronic boards.
Net-net, this could turn out to be a good JV!
That's all for this edition. Have a great Sunday!
Disclaimer: None or buy or sell recommendations. This publicly available information is shared for learning and education purposes.
Investors are closely watching Supriya Lifescience as it attempts to rebound from operational hiccups and hit ambitious revenue targets.
Nike's market cap hit a peak of $280B in November 2021. It's now down to $57B (a $223B drop) and will be delisted from S&P 100.
Former Nike branding exec Massimo Giunco wrote a viral post in 2024 laying it all out. He blamed CEO John Donahoe (2020-2024) for going all in on direct-to-consumer (DTC)...with a cameo from McKinsey:
▫️ELIMINATE CATEGORIES: McKinsey advised Nike to get rid of categories (running, basketball, soccer) and re-classify everything into “Women”, “Men” and “Kids”.
The logic was that Nike was duplicating resources and a pivot to DTC would provide enough customer data to inform product decisions instead of relying on the category experts (eg. a basketball vet that spent 20+ years at Nike). A lot of these experts were fired and Nike lost their insights.
This was a clear L because Nike quietly brought back categories at end 2023.
▫️END WHOLESALE LEADERSHIP: Nike ended hundreds of relationships with wholesales partners and prioritized Nike's website over retail.
The change looked genius during COVID but as customers returned to brick ‘n mortar, Nike’s product were nowhere to be found. It had burnt bridges with partners, who were happy to give shelf space to upstarts (this wasn’t covered but I think On and Hoka took advantage of this for running)
There was also a lack of feedback from retailers, which led to inventory issues (the “data-driven” insights from online sales proved to not be a panacea).
▫️PRIORITIZE DIGITAL MARKETING: Nike changed its marketing budget to focus on driving users to Nike digital properties and membership platforms.
For decades, Nike spent 10% of sales on brand advertising to create an aspirational halo. The prioritization of programmatic ad spend meant Nike went from “create demand” (new customers) to “serve and retain demand” (re-targeting existing ones).
The result was a slowdown in sales.
“Because of that,” writes Massimo Giunco (who spent 21 years at the company), “Nike invested a material amount of dollars (billions) into something that was less effective but easier to be measured vs something that was more effective but less easy to be measured. In conclusion: an impressive waste of money.”
The quality of advertising was also...not great.
***
The focus on DTC is not surprising. Donahue was formerly CEO of B2B SAAS firm ServiceNow.
Nike’s DTC business peaked at 44% of sales in 2024 (vs. under 30% before the strategy change).
The digital focus seems to have commoditized the product, impacted Nike’s brand perception and created an opening for competitors.
***
Original post: https://www.linkedin.com/pulse/nike-epic-saga-value-destruction-massimo-giunco-llplf/
Nike's disastrous pivot to direct-to-consumer sales has culminated in a humiliating exit from the S&P 100.
IRIB claims Iran targeted three vessels in the Strait of Hormuz and three American ships. Tehran says the strike is retaliation for U.S. attacks on three Iranian tankers.
A rapid escalation in the Strait of Hormuz threatens global energy markets as Tehran directly engages American naval assets.
China still refines 90%+ of the world’s rare earths.Tesla just built a production EV motor that uses none of them.
The Cybercab drive unit contains zero neodymium, praseodymium, dysprosium, or terbium. Elon Musk says it still matches full vehicle range. He called that “extremely hard to achieve.”
The 163 kW unit is 18% smaller, 25% lighter, and designed for fully automated, sub-10-second assembly.
Most EV motors still depend on Chinese-processed magnets that can account for 25–35% of motor material cost. This one doesn’t.
The Austin fleet is small, and Tesla’s other cars still use rare-earth motors. Wind, robots, and defense still need those magnets.
But the monopoly is no longer a technical requirement. A high-efficiency traction motor can now be built without going through China’s refining system.That is the part that matters.
Tesla's engineering breakthrough on the Cybercab severs a critical supply chain vulnerability tied to Chinese rare earth monopolies.
"We have to accept the possibility that all mathematics could fall to AI within some months, however unsettling that might seem."
The part of mathematics that is like playing Chess or Go, coming up with ever cleverer moves, will be conquered by AI. That is now evident.
The part of mathematics that is like inventing an entire new game like Chess _that humans would consider interesting_ is much harder but then humans do that very very rarely too. The "humans would consider interesting" could be considered a fundamental limit of AI or merely a face-saving formula to protect human ego but humans set the rules (for now!).
Where does programming fit here? It increasingly seems to me that a very large fraction of software code could be produced competently and _correctly_ by AI. The "correctly" part is being addressed with proof systems like Lean that are applied to mathematical theorem proving today but soon will be applied to verify the software code produced by AI.
The point is not that "AI will do it all". There will be humans involved in the process. The key question is "how many humans are needed" and the answer right now is sobering and unsettling.
All of us in software need to figure out how to stay relevant. Let me get back to work. Please wish us luck 🙏
The rapid advancement of reasoning models is forcing tech leaders to confront the imminent automation of high-level mathematics.
Timepass talk on Sunday
1. Supriya Lifescience
FY27 is projected to be a transformative growth year, with management maintaining firm guidance to reach the ₹1,000 crore revenue milestone while targeting normalized EBITDA margins of 33% to 35%.
Despite initial Q1 FY27 disruptions caused by transient headwinds like water scarcity at Lote and solar policy changes, performance is expected to recover non-linearly. Growth will be heavily back-ended in H2 FY27 as production normalizes, inventory liquidates, and deferred Q1 sales of ₹35 crore are recovered without major operational downtime from annual maintenance.
Management also clarified that that the customs issue was limited strictly to this specific shipment, does not impact other exports or product licenses, and will have no material impact on operations or financial guidance. The company has already received a fresh CBN export permit to regularize the consignment.
The primary revenue drivers for the year center around new product commercialization and expanding therapeutic focus areas.
Key catalysts include the scale-up of two recently launched liquid anesthetic inhalation products, upcoming pipeline launches in the ADHD segment, and the H2 FY27 launch of contrast media products (iohexol). These additions build upon healthy momentum across core product portfolios, such as cardiovascular advanced intermediates and established lines in anesthetics, anti-anxiety, vitamins, and anti-diabetics. Furthermore, a strong export footprint, which accounts for 81% of revenue, along with deep backward integration (72% fully integrated) provides significant structural support to protect profit margins.
Longer-term infrastructure and regulatory milestones scheduled throughout FY27 will further bolster execution and open new market corridors.
The newly operational Ambernath facility is advancing its CMO/CDMO vertical for finished formulations (tablets, injectables) following scheduled regulated market audits, such as the EU audit in late November 2026.
Simultaneously, initial phase construction is underway at the Patalganga (Isambe) facility, backed by a ₹200 crore Phase-1 CapEx allocation for new API and intermediate blocks, to expand long-term production capacity. Coupled with upcoming CEP approvals for European markets and ongoing SAP digital integration, these developments establish a robust structural foundation for sustainable growth through FY27 and beyond.
The company also indicated that it has made good progress on a large anesthetic CDMO contract and is now very close to signing a term sheet. If timelines hold, it expects to make a positive announcement in the next quarter.
2. MRI, Gadolinium and Manganese
Approximately one-third of all MRI scans worldwide (~65 million procedures annually) require a contrast agent to clearly visualize tumors, lesions, vascular abnormalities, or tissue damage.
Gadolinium-Based Contrast Agents (GBCAs) like gadobutrol are the most commonly used.
However, GBCAs carry couple of disadvantages
i). Because gadolinium is a non-essential heavy metal, small traces can remain deposited in human bones, brain tissue, and skin, posing potential risks for pediatric patients or individuals requiring frequent follow-up scans.
ii). As a rare-earth element, gadolinium's global supply chain is heavily concentrated in China, leaving healthcare systems around the world vulnerable to geopolitical trade disruptions and supply shortages for critical diagnostic imaging.
The Alternative: GE HealthCare’s novel investigational agent, mangaciclanol, replaces traditional gadolinium with manganese, a naturally occurring, body-regulated mineral, and has earned FDA Fast Track designation as it advances through Phase 2/3 LUMINA clinical trials to offer a safer, environmentally friendly, and supply-resilient alternative for contrast-enhanced MRI scans in both adult and pediatric patients.
Because manganese is an essential nutrient already metabolized by the body, macrocyclic manganese agents offer a significantly safer profile.
If this approval is thru, it would be good for all patients needing to go thru MRI scans!
Of course, this could be 2-3 years away!
3. The $55 Trillion Nuclear Supercycle
Jefferies initiated coverage on the global nuclear sector, framing it as entering its strongest growth cycle in four decades. Citing compounding power demand from hyperscale data centers, physical AI, and widespread electrification, the brokerage estimates roughly $55 trillion in global nuclear-related capex through 2100, including $9 trillion by 2050 to replace aging global reactor fleets. Recognizing structural supply deficits in primary fuel, Jefferies raised its long-term uranium price outlook and issued Buy ratings on key global miners, developers, and specialized component makers like Cameco, NexGen Energy, and BWX Technologies.
This massive structural capex creates high-margin second-order opportunities for manufacturing, engineering, and infrastructure suppliers. Nuclear plant construction relies heavily on precision-engineered components, specialized metallurgy, and high-pressure flow control systems that must meet stringent nuclear regulatory standards. Companies in adjacent sectors, such as high-grade alloy forging, specialized pipe spooling, custom mechanical sealing, and high-voltage grid transmission, stand to gain pricing power and margin expansion as localized supply chains scale up to build both traditional Pressurised Heavy Water Reactors (PHWRs) and next-generation Small Modular Reactors (SMRs).
Of course, India itself has articulated an ambition of ~100 GW nuclear capacity by 2047 (from ~8 GW currently), implying a significant scale-up over the next two decades.
In India, several companies are prime candidates to capture these indirect equipment and infrastructure tailwinds if and when the supply chain expands to India.
It’s quite evident that Larsen & Toubro and Bharat Heavy Electricals Limited lead the pack. In particular, the scale and contribution of L&T is truly impressive.
Walchandnagar Industries: Appears to be a relatively pure-play on the nuclear segment. However, the lack of concalls and regular investor communication makes it difficult to assess the company’s direction and execution.
Kilburn Engineering: Around 1/4th of its order book is from the nuclear power segment. It supplies pump room coolers, vault coolers and heavy-water vapour recovery systems.
MTAR Technologies: A specialized player supplying components for fuel transfer systems.
KSB Pumps: Another specialized supplier, particularly in coolant pumps. Earlier this year, it also received an export order from Europe.
Unimech Aerospace: Has an interesting nuclear order book and is qualified across 10 different subsystems, which could provide multiple avenues for growth.
Again, nuclear is a long-gestation theme, and the actual earnings curve can differ significantly from one player to another.
The opportunity may be large, but the timing of revenue, order conversion and earnings will not be uniform across companies.
4. Thermax
Thermax faced a challenging Q1 FY27 primarily due to a severe financial hit in its Industrial Infra segment, where a cost-to-completion revision on a legacy, loss-making government EPC project resulted in an unexpected hit of ₹91 crore. This was triggered by late structural design changes mandated by an external engineering partner.
Operational execution was further hindered by shipping delays of finished goods inventory worth approximately ₹300 crore, largely caused by high freight rates and Middle East logistics disruptions, which postponed revenue recognition. Profitability was additionally compressed by an ₹18 crore rise in raw material commodity costs (mainly steel), alongside a ₹20 crore loss in First Energy Private Limited (FEPL) due to bureaucratic approval delays on completed Tamil Nadu projects and high manpower carrying costs.
Outlook for the Rest of FY27
Despite the weak start, management remains bullish on the rest of FY27, citing a strong and high-quality order backlog that will drive robust revenue and margin conversion in Q2, Q3, and Q4. Revenue execution is expected to ramp up significantly, with the company aiming to achieve quarterly revenues exceeding ₹3,000 crore for two to three of the remaining quarters.
Furthermore, profitability is projected to recover sharply as high-margin international export orders (such as U.S. data center equipment shipments) get recognized, commodity price pressures flush out of Industrial Products, and legacy government/FGD project exposures systematically wrap up to near-zero by the end of the fiscal year.
On August 6, 2026, the Union Cabinet approved GOBARdhan (National Circular Bioenergy Scheme) with a total outlay of ₹23,731 crore ($2.5 billion).
The policy, effective September 1, 2026 through FY2035–36, offers several incentives, including a significant increase in the procurement price to ₹2,110/MMBTU, up from ₹1,478/MMBTU. This should now open up good pipeline for Thermax.
Future Growth Drivers
Thermax’s multi-year growth trajectory is anchored across several key segments:
Data Center Infrastructure & Export Expansion: The company is expanding high-margin cooling solutions (absorption chillers and hybrid CLCTs) and specialized boiler pressure parts for power projects serving U.S. and Indian data centers.
Thermal Power & TBWES Capacity: Surging national and global demand for thermal, captive power, and subcritical/supercritical boiler capacity is driving a substantial pipeline, prompting Thermax to expand internal manufacturing and ecosystem capacity.
Clean Energy & Green Solutions: Thermax is positioned to capture policy-driven growth in Bio-CNG (via expected central pricing and mandate revisions), Green Methanol (underway with its showcase Kandla Port project), and Green Hydrogen/SOEC demo technology through its partnership with HydrogenPro.
Industrial Products & Green Upgrades: Core double-digit growth is sustained through industrial sustainability requirements, particularly Zero Liquid Discharge (ZLD) water plants, industrial air pollution control retrofits, and high-margin utility offerings via Thermax Onsite Energy Solutions Limited (TOESL).
5. Avalon Technologies
Avalon Technologies announced a joint venture (JV) with Germany-based Zollner Elektronik AG, one of Europe’s largest Electronics Manufacturing Services (EMS) players.
The entity will be incorporated as Zollner Avalon Private Limited and will serve as an India-based manufacturing platform for high-complexity electronics.
Core Structure & Equity Mechanics
Initial Ownership Split: Zollner will hold 51% and Avalon will hold 49%.
Call Option for Majority Stake: Avalon retains a call option to acquire an additional 2% stake (taking its shareholding to 51%) after the 3rd anniversary of commercial production commencing at the plant, contingent on agreed valuation parameters.
Although Avalon is a 49% minority shareholder, meaning the JV's top-line revenue and EBITDA won't directly consolidate into Avalon’s primary P&L lines, its 49% share of net profits will directly boost PAT via equity accounting.
Beyond its 49% equity share, Avalon will act as a direct component supplier to the JV, supplying cable wiring & harnesses, magnetics, plastics, sheet metal, and precision machining. This creates a dual revenue stream (equity share + component vendor supply).
Zollner brings six decades of German engineering practices, specifically in high-density, complex Surface Mount Technology (SMT) and multi-layered Printed Circuit Board Assembly (PCBA) processes.
Likewise, Zollner operates extensively in lifecycle management, advanced automated optical/X-ray inspection systems, and high-reliability functional testing suited for mission-critical applications.
Operating alongside a Top-10 global EMS player transfers operational "know-how", including German manufacturing quality control, traceability protocols, and supply chain standardization, directly into the JV's Indian operations.
Expansion into Strict Industry Verticals
Healthcare & Life Sciences: Medical-grade electronics require specialized manufacturing standards (such as ISO 13485 certifications) and zero-defect quality systems that Zollner operates globally.
Rail & Transport Infrastructure: High-reliability mechatronic assemblies that can withstand extreme vibration and temperature ranges.
Test & Measurement: Ultra-high precision, low-noise electronic boards.
Net-net, this could turn out to be a good JV!
That's all for this edition. Have a great Sunday!
Disclaimer: None or buy or sell recommendations. This publicly available information is shared for learning and education purposes.
Investors are closely watching Supriya Lifescience as it attempts to rebound from operational hiccups and hit ambitious revenue targets.
🇷🇺🇺🇸 Witkoff and Kushner have left the Kremlin after roughly 3.5 hours with Putin.
No statements. No readout.
Now they’re heading to Kyiv to meet Ukrainian officials.
Whatever was said in that room is traveling with them.
Source: @TabzLIVE on TG / Writer: Oliver
Back-channel diplomacy between the incoming Trump administration and Moscow is accelerating as key envoys shuttle directly to Kyiv.
People who think Office, Teams, or Outlook coming to Linux as native apps are stuck in a pre-@satyanadella idea of Microsoft. This was the memo 10 years ago!! https://www.microsoft.com/en-us/windows-server/blog/2015/05/06/microsoft-loves-linux/
Microsoft bringing its core productivity suite natively to Linux completes a decade-long cultural pivot initiated by Satya Nadella.
Claude Fable 5.1 (Max) by @AnthropicAI has landed in the Agent Arena at #1 with +15.8% net improvement across 6.7k+ real-world agentic sessions! It also redraws the price-performance frontier: #1 on the leaderboard at a median cost of $4.14/task.
By signal, Claude Fable 5.1 sees a massive lead in implicit user sentiment with an astonishing (+42.5%) in Praise vs. Complaint. Users are praising it around 2x more often than the next top model. It also sees strong explicit feedback via Confirmed Success (+22.4%), and solid Bash Recovery (+13.1%), with no Tool Hallucinations. More detail on its performance by signal below.
Claude Fable 5.1 (Max) out ranks all past Claude variants and the rest of the pack by a healthy lead.
In Agent Arena, we measure models on millions of long-horizon agentic tasks from a global community of users. Models can access web search, filesystem, and terminal tools to complete complex workflows. The leaderboard measures model performance on outcomes relative to the average model using a causal tracing methodology.
Stay tuned as traces continue to come in for the latest GPT-6 Astra to see how it compares. Use Agent Mode to contribute to the real-world rankings.
Congrats again to @AnthropicAI for this release.
Anthropic's newest model is dominating agentic benchmarks while drastically undercutting competitors on price.